Fixed vs. Variable Rate: Which Structure Fits Your Strategy? One of the most critical decisions when structuring a mortgage is deciding between a fixed rate, a variable rate, or a split loan structure. Understanding your options: • Fixed Rates: Provide budget certainty with locked-in repayments, but often limit extra repayments and redraw access. • Variable Rates: Offer flexibility with features like offset accounts and unlimited extra repayments, but fluctuate with market changes. • Split Loans: Combine both strategies, giving you repayment stability on one portion and feature flexibility on the other. Every borrower's situation is different. We analyze your goals to help you choose the right balance.
Learn more: Fixed vs. Variable Rate: Which Structure Fits Your Strategy? One…Mortgage broker · Merrylands
Stamp duty calculator
Estimate stamp duty, mortgage registration and transfer fees, and any grants you may be eligible for.
Credit Representative 526611 of Mortgage Specialists Pty Ltd (ACL 387025)5 from 58 Google reviews
Results are estimates based on the information you enter. They are not a loan offer or credit advice. Speak with a broker to confirm what you may qualify for.
Assumptions to know
Rates and concessions are set by each state and change over time; confirm with Revenue NSW before you sign.
FAQs
Do first home buyers pay stamp duty in NSW?
It depends. Mortgage Pass in Merrylands points first home buyers to Revenue NSW, which sets the thresholds by price and by whether the home is new or existing.
Talk to a broker in Merrylands
Book a time that suits you, or call us now.
Business information
Mortgage Pass
Address
1/219 Merrylands Road, Merrylands NSW 2160Get directions →
Phone
Booking link
Hours
HoursSee all →
Website
Plus Code & geo
Credit licence
Australian Credit Licence 387025
Licensed, and on your side
Mortgage Pass is Credit Representative 526611 of Mortgage Specialists Pty Ltd, Australian Credit Licence 387025.
Best interests duty
By law, we must act in your best interests when we recommend a loan, and we explain in writing why we chose it.
A real comparison
We compare loans from 35+ lenders, including major banks and specialist lenders, not one bank's range.
Industry member
Julie Judge is a member of the Mortgage & Finance Association of Australia (MFAA) and holds a Diploma of Finance and Mortgage Broking Management.
Find us
Hours, directions and map
- Address1/219 Merrylands Road
Merrylands NSW 2160 - StatusHours
- Google Plus Code
5X7Q+HH
Opening hours
HoursMonday9:00 am – 6:00 pm
Tuesday9:00 am – 6:00 pm
Wednesday9:00 am – 6:00 pm
ThursdayToday9:00 am – 6:00 pm
Friday9:00 am – 6:00 pm
SaturdayClosed
SundayClosed
Status: Open today 9:00 am – 6:00 pm
What’s new
Latest from Google
Fresh updates, offers and news straight from our Google Business Profile.
Streamline Your Finances: How Debt Consolidation Works Managing multiple high-interest debts (such as credit cards, personal loans, or car finance) can put unnecessary pressure on your monthly cash flow. By leveraging the equity in your residential property, you may be able to consolidate high-interest debts into your lower-rate home loan. The benefits of refinancing to consolidate debt: • One Clear Repayment: Replace multiple due dates with a single structured monthly payment. • Lower Overall Interest Rates: Shift high-rate consumer debt to competitive home loan rates. • Improved Monthly Cash Flow: Lower your immediate total monthly commitments. Speak with the Mortgage Pass team to evaluate if equity release is the right strategy for your financial position!
Book: Streamline Your Finances: How Debt Consolidation Works Managing…
Navigating First Home Buyer Schemes in 2026 Getting into your first home doesn't always require a massive 20% deposit. Australian first-home buyers have access to key government initiatives and loan structures designed to fast-track your approval: • 5% Deposit Schemes: Buy sooner without paying hefty Lenders Mortgage Insurance (LMI). • Stamp Duty Exemptions: Depending on your state and property value, save tens of thousands at settlement. • Shared Equity Options: Partner with state programs to lower your upfront contribution. Navigating eligibility rules can be tricky. We map out your options and find the right lender for your budget.
Book: Navigating First Home Buyer Schemes in 2026 Getting into your…
Is Your Mortgage Costing You Loyalty Tax? Banks rarely offer their best interest rates to existing customers. Over time, "rate creep" means long-term borrowers often pay significantly higher interest rates than new applicants at the exact same bank. Why conduct a mortgage health check? • Lower Monthly Repayments: Free up cash flow for household expenses or business growth. • Unlock Equity: Tap into your home’s value for debt consolidation or property investment. • Feature Upgrades: Switch to loans offering multiple offset accounts or fee-free redraw facilities. A quick 15-minute review could save you thousands each year.
Book: Is Your Mortgage Costing You Loyalty Tax? Banks rarely offer their…
Self-Employed? How Low-Doc Loans Help You Secure a Mortgage Running your own business shouldn't stand between you and homeownership. Traditional lenders often struggle to assess self-employed income, especially if your recent tax returns don't reflect your current cash flow. How we help self-employed borrowers: • Alt-Doc Options: Verify income using BAS statements, accountant letters, or business bank statements instead of full tax returns. • Add-Back Optimisation: Properly account for depreciation, one-off expenses, and director fees to maximize borrowing capacity. • Lender Selection: Match your business structure with lenders who specialize in commercial and self-employed lending.
Book: Self-Employed? How Low-Doc Loans Help You Secure a Mortgage…
Case Study: How two brothers bought their first home with $0 deposit The Situation: • Working hard with strong incomes, but $0 saved for a cash deposit • Stuck in the rental trap while property prices kept rising The Strategy (Family Guarantee): • Used their mum’s equity as a guarantor so they didn't need to save a full cash deposit • Avoided paying Lenders Mortgage Insurance (LMI) completely, saving thousands • Fast-tracked straight from renting to owning their first property Parents: You can help your children get onto the property ladder without handing over cash. Reach out to the Mortgage Pass team to explore how a guarantor loan works!
Learn more: Case Study: How two brothers bought their first home with $0…
Business Owners: Turn your home equity into long-term wealth. Common challenges we solve: • Banks not understanding business income • Fear of over-leveraging or making the wrong move • Unsure whether to renovate, refinance, or invest How we structure your finance: • Use property equity strategically, not emotionally • Improve cash flow while keeping loan flexibility • Plan for the next 5 to 10 years, not just today #firsthomebuyer #Sydneymortgagebroker #Sydneybusinessowner #PropertyInvestmentAustralia #SydneyRealEstate
Book: Business Owners: Turn your home equity into long-term wealth.…
Planning a Renovation? How Construction Loans Work Funding a major build or renovation is very different from buying an established home. Instead of receiving a single lump sum, construction finance is released in stages as work is completed. Key benefits of a structured construction loan: • Progress Draws: You only pay interest on the money released to the builder at each stage. • Valuation Safety: Lenders assess the loan based on the projected on-completion value of your home. • Cash Flow Control: Keep repayments manageable while your build is underway. Planning to extend or upgrade? Let’s organize your finance structure before you sign builder contracts!
Learn more: Planning a Renovation? How Construction Loans Work Funding a major…
Renovating or Building? How to Finance Your Dream Space Thinking about upgrading your home rather than selling? Structuring your renovation finance correctly can save you tens of thousands in interest while boosting your property value. Ways to finance your home improvement: • Unlocking existing equity in your current mortgage • Construction loans with staged progress payments • Redraw facility or offset account options Before you start knocking down walls, let’s make sure your finance structure works for you. #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Learn more: Renovating or Building? How to Finance Your Dream Space Thinking…
Chasing the "lowest interest rate" is usually a trap. For business owners, real refinancing isn't just about a headline rate—it's about how your loan is structured. Smart refinancing should focus on: • Freeing up daily cash flow • Unlocking trapped property equity • Creating flexibility for your next big move A rigid rate can limit your growth. Your loan should build your lifestyle, not restrict it. Talk to the team at Mortgage Pass today to review your options. #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Book: Chasing the "lowest interest rate" is usually a trap. For business…
Case Study: Is your home loan secretly costing you thousands? A recent client assumed his $550k home loan was completely fine. After a quick review of his interest rate and loan structure, the numbers spoke for themselves: • $74 lost every single day • $519 drained every week • $2,250 wasted every month By restructuring his loan, we saved him over $27,000 a year in cash flow. Has it been over 12 months since your last mortgage review? Reach out to the Mortgage Pass team today. #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Book: Case Study: Is your home loan secretly costing you thousands? A…
Self-Employed & Need a Home Loan? Your Accountant & Broker Need to Speak the Same Language. Getting approved for a mortgage when you run a business requires a clear strategy. We work directly with your accountant to present your financials accurately to lenders. What we focus on for self-employed borrowers: • Understanding your complete income, asset, and liability position • Utilizing low-doc and alternative income verification loans • Structuring your mortgage to support business growth and tax efficiency #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Learn more: Self-Employed & Need a Home Loan? Your Accountant & Broker Need to…
You do not have to put your future on hold. Waiting for the perfect timing, market shift, or partner to secure your ideal property is a trap. True freedom starts with owning your space, taking control of your financial position, and building long-term security on your own terms. Your dream home is entirely achievable right now with the right strategy in place. Ready to make your move? Contact us today to map out your home buying path. #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Book: You do not have to put your future on hold. Waiting for the…
It is easy to get caught up in bed counts, land sizes, and postcode searches. The real secret to finding the right home goes beyond the physical layout. It comes down to lifestyle. How your morning routine flows, how your space supports your work, and how your environment feels after a long day matter far more than square footage alone. When you align your finance strategy with the life you actually want to live, buying or renovating becomes a seamless step forward. Ready to make your next property move with complete clarity? Contact us today to map out your finance strategy. #FinanceStrategy #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Book: It is easy to get caught up in bed counts, land sizes, and…
Most people only ask if they have enough cash in their account to make a purchase today. True financial freedom happens when you shift your focus toward long-term sustainability instead. When you evaluate the total cost of sustaining a lifestyle, your choices naturally align with building lasting wealth. It is never just about making the purchase. It is about protecting your peace and keeping your momentum. Send us a message today to start building a clear path toward your financial goals. #firsthomebuyer #Sydneymortgagebroker #Sydneyfirsthomebuyer #PropertyInvestmentAustralia #SydneyRealEstate
Book: Most people only ask if they have enough cash in their account to…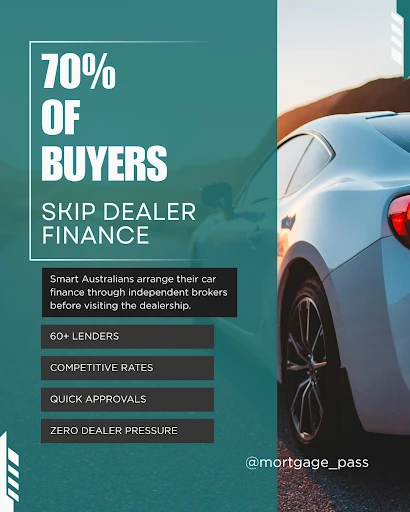
Australia recently recorded its strongest July on record with 103,656 new vehicle deliveries, following the biggest month ever in June. Nearly nine in ten buyers finance their vehicles, but only 30% to 35% arrange that finance through the dealership. Around 70% choose their own bank, comparison sites, or independent brokers to secure better options for their budgets. Planning your next vehicle upgrade? Explore over 60 lenders with Mortgage Pass to find the right loan structure: https://mortgagepass.com.au/car-loans/
Learn more: Australia recently recorded its strongest July on record with…
No one talks enough about how expensive confusion really is. When you avoid looking at your numbers, those numbers do not just sit there. They quietly start controlling your growth, limiting your choices, and dictating your future decisions. True confidence in business does not come from guessing or playing it safe. It comes from absolute financial clarity. When you understand your position, you stop operating out of fear and start taking strategic control of your wealth. Ready to gain full clarity over your finance and debt strategy? Contact us today to map out your next move.
Book: No one talks enough about how expensive confusion really is. When…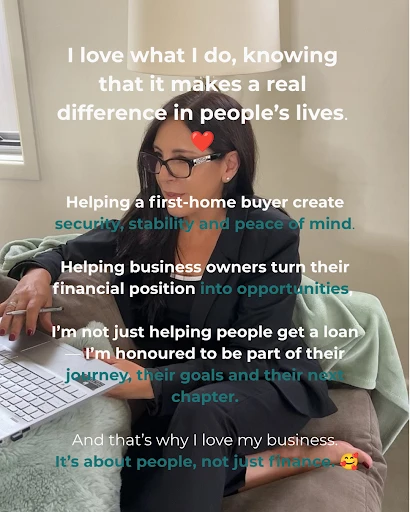
One of the things I love most about what I do is knowing that it makes a real difference in people’s lives. ❤️ Helping a first-home buyer create security, stability and peace of mind. Helping business owners turn their financial position into opportunities, whether that’s buying property, refinancing, renovating or growing their business. I’m not just helping people get a loan — I’m honoured to be part of their journey, their goals and their next chapter. And that’s why I love my business. It’s about people, not just finance. 🥰 #firsthomebuyer #lovemybusiness #homebuyer #helpingpeople #buyingproperty #helpingbusiness #realdifference
Learn more: One of the things I love most about what I do is knowing that it…
Self-employed borrowers often get turned down by traditional banks simply because standard payroll templates fail to reflect their actual income. Traditional lenders focus on rigid pay slips, while true borrowing capacity relies on real cash flow, depreciation, and allowable add-backs. Working with an expert who understands business structures transforms how lenders view your financial position. We specialize in analyzing the complete picture, helping business owners move from high-interest rates to major banks or transition from paying commercial rent to owning their own space. Reach out to Mortgage Pass today to book your assessment call and see what your business can actually achieve.
Book: Self-employed borrowers often get turned down by traditional banks…
They missed the first allocation for the government scheme and almost gave up. We watched the market like a hawk, pounced when new spots opened, and saved them thousands in LMI!
Book: They missed the first allocation for the government scheme and…
Most people wait years to buy property because they think 20% down is mandatory. Flexible low-deposit options let you fast-track your homeownership goals today. Head to our website to check your options.
Book: Most people wait years to buy property because they think 20% down…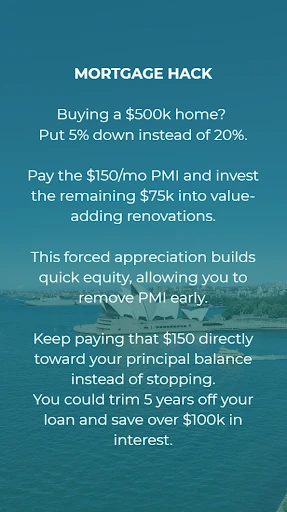
Smart buyers keep their cash, renovate to build fast equity, and drop their mortgage years early. Reach out to Mortgage Pass to structure your loan for maximum growth, preserve your upfront capital, and build long-term wealth faster. Link is in our bio!
Learn more: Smart buyers keep their cash, renovate to build fast equity, and…
Continuing to learn, connect and stay ahead of the industry. I recently attended IFBF, where I had the opportunity to hear from inspiring women in finance and connect with fellow brokers. Events like this are valuable because brokers learn from each other through education, industry updates and real-life lending scenarios — ultimately helping us provide better guidance to our clients. Proud to be part of an industry that continues to evolve. #MortgageBroker #MortgagePass #SydneyMortgageBroker #FinanceIndustry #WomenInFinance #finance #woman #womeninfinance #sharingexperience #accomplishedwoman #ifbf #accomplishedwomen #beinspiring #confidence
Learn more: Continuing to learn, connect and stay ahead of the industry. I…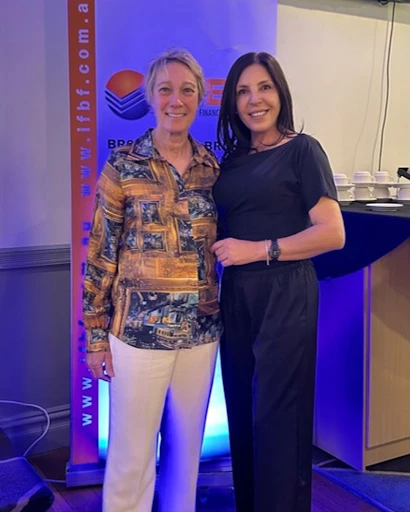
It's a privilege to attend IFBF and hear from Tanya Sale, CEO of Outsource Financial and the first woman in Australia to lead an aggregator. Tanya shared valuable insights into our industry, including that brokers now hold an incredible 81% market share. What impressed me most was seeing a woman leading at such a high level in our industry. I love events like this — where brokers support brokers through education, industry updates and real-life scenarios. Always learning. Always growing. 🤝 #ceo #privilege #industryupdate #financial #ifbf #educationindustry #woman #industry #learning #education
Learn more: It's a privilege to attend IFBF and hear from Tanya Sale, CEO of…