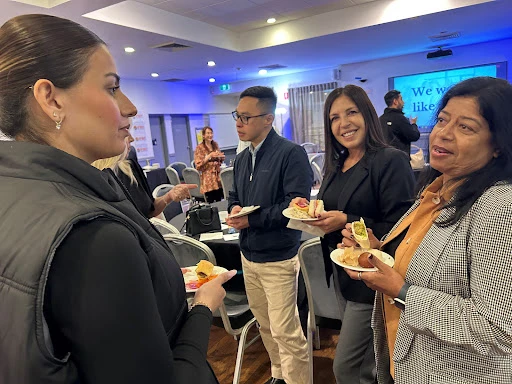
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…A practical guide to borrowing power, income assessments, upfront deposit costs, pre-approvals, and property settlement steps for Merrylands home buyers.
On this page
Buying a home in Merrylands requires clear financial planning before you begin inspecting properties or attending auctions. Borrowers need to know how much a bank will lend them, how different types of income affect their borrowing capacity, and what upfront cash is required beyond the property deposit. Understanding how lenders assess property types, variable earnings, and credit limits helps avoid delays or unexpected loan declines. Establishing your budget early ensures you can search for property with confidence.
How lenders calculate your borrowing power
Your total borrowing capacity depends on how credit providers evaluate your taxable income, household living expenses, and existing personal debts. Every bank applies distinct serviceability criteria, which means two lenders can give you significantly different borrowing limits for the same salary.
Lenders treat base salary differently from variable earnings such as overtime, commission, bonuses, or contracting income. While base pay is usually calculated at full value, variable income is often shaded or averaged over one to two years to account for fluctuating earnings.
Credit providers also apply an interest rate serviceability buffer to ensure you can maintain repayments if interest rates rise. Checking your borrowing limits across multiple options helps set an accurate budget. You can test potential borrowing scenarios using a borrowing power calculator before searching for property.
Deposits, Lenders Mortgage Insurance, and upfront costs
Upfront purchase funds must cover your property deposit alongside government statutory charges like NSW transfer duty. While a 20 percent deposit is traditional, lower deposit options exist depending on lender criteria and buyer circumstances.
Buying with a deposit under 20 percent generally incurs Lenders Mortgage Insurance. This insurance protects the lender if a borrower defaults on repayments, and the premium cost is typically added to your total loan amount or paid upfront.
Additional transaction fees include conveyancing costs, building and pest inspections, and mortgage registration charges. Estimating statutory duties using a stamp duty calculator ensures your initial savings cover all acquisition expenses before contracts are exchanged.
Evaluating freehold houses versus strata units
The type of property you choose influences purchase costs and how a lender assesses the asset for a home loan. Houses involve individual title searches, whereas strata apartments require an evaluation of body corporate records, building funds, and ongoing levies.
Credit providers examine strata schemes to verify that capital works funds, admin funds, and building insurance meet credit requirements. High monthly levies are factored directly into your ongoing living expenses, which reduces your calculated borrowing power.
Lenders also assess unit sizes and high-density location risks, which can alter minimum deposit requirements. Knowing these criteria before making an offer prevents last-minute hurdles during asset valuation.
The steps from pre-approval to final settlement
Pre-approval gives you a conditional agreement from a lender based on verified income, savings, and expense documents. Holding a current pre-approval confirms your maximum spending limit, allowing you to bid at auction or negotiate private treaty sales within clear boundaries.
Once your offer is accepted or you win at auction, the lender orders a property valuation to confirm the asset provides adequate security. Satisfying all remaining lender conditions transforms your conditional pre-approval into formal unconditional approval.
After formal approval, loan contracts are issued for signing and legal representatives arrange final funds transfer for settlement day. If you wish to adjust loan structures or evaluate lower rate options in the future, assessing refinance savings provides useful long-term context.
Applying for finance when self-employed or on complex income
Self-employed applicants, sole traders, and company directors supply different income verification compared to salaried employees. Lenders generally review two years of personal tax returns, company financial statements, and notices of assessment to verify ongoing business income.
Income streams flowing through trusts, partnerships, or complex company structures require thorough documentation to prove recurring earnings. Organised financial records help demonstrate trading history and cash flow stability to credit assessors.
Applicants with short trading histories or non-standard documentation can evaluate tailored self-employed loans that match their business structure. Presenting clear financial summaries ensures credit providers assess your application accurately.
How Mortgage Pass helps
Mortgage Pass is a mortgage broker based at 1/219 Merrylands Road, Merrylands NSW 2160. Director and founder Julie Judge holds a Diploma of Finance and Mortgage Broking Management, is an MFAA member, and is legally required under best interests duty to recommend suitable loans. Having worked for years with businesses in building, fresh produce, and retail, Julie reads financial statements from a lender's perspective. Mortgage Pass compares home loan options across 35+ lenders to assist home buyers, self-employed borrowers, and investors in Merrylands and surrounding areas. Contact Mortgage Pass on 0455 510 512 or info@mortgagepass.com.au.
Frequently asked questions
How do strata levies affect my borrowing power?
Credit providers factor ongoing strata levies directly into your living expenses. High monthly levies increase your calculated household expenses, which directly reduces your total borrowing capacity.
What upfront expenses apply when buying a home besides the deposit?
Upfront costs include statutory charges such as NSW transfer duty, conveyancing costs, building and pest inspections, and mortgage registration fees. Paying a deposit under 20 percent may also incur Lenders Mortgage Insurance.
What income documents do self-employed borrowers need to provide?
Lenders typically review two years of personal tax returns, company financial statements, and notices of assessment. Income running through trusts or complex structures requires thorough financial documentation to prove recurring earnings.
What happens after an offer is accepted with conditional pre-approval?
The lender orders a property valuation to verify that the asset offers adequate loan security. Meeting all remaining lender conditions then converts conditional pre-approval into formal unconditional approval.
Understanding borrowing limits, deposit requirements, and property assessment criteria prepares you for buying a home in Merrylands. Comparing credit policies across multiple lenders helps secure finance tailored to your financial circumstances. Determining your true borrowing capacity early gives you confidence when negotiating or bidding at auction.