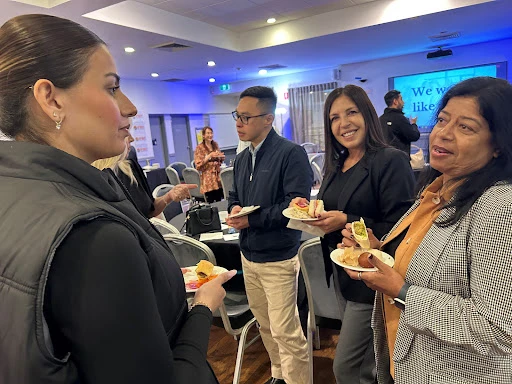
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…A practical guide to how lenders assess shop-fronts, mixed-use buildings, strata offices and light industrial units in Western Sydney.
On this page
- How does property classification affect your loan options?
- Shop-top and mixed-use property considerations
- Financing offices and professional suites
- What checks are needed before making an offer on commercial property?
- How lenders evaluate commercial borrowing capacity
- How Mortgage Pass helps
- Frequently asked questions
Purchasing commercial real estate across Merrylands, Granville and Parramatta involves dynamic lending rules that differ from residential buying. Commercial lenders focus heavily on property risk, local council zoning, lease stability and overall business cash flow. Whether you are expanding an operating business or investing in commercial premises, understanding how credit officers view commercial assets helps avoid unnecessary delays during contract negotiations.
How does property classification affect your loan options?
Commercial property across Western Sydney spans several distinct categories, including retail shop-fronts, mixed-use buildings, strata office suites and light industrial warehouses.
Retail shop-fronts and customer-facing trading sites are evaluated on foot traffic, location stability and the strength of surrounding commercial precincts.
Light industrial units and storage warehouses cater to trade operations, manufacturing and logistics businesses. Lenders look closely at vehicle access, clearance heights and general utility when determining property liquidity.
Strata office suites accommodate professional service providers such as accountants, legal practices and consultants. Bank credit teams assess the overall strata plan, maintenance registers and tenant turnover within the building.
Higher risk property classifications or specialized premises may lead lenders to request larger deposit contributions and apply shorter loan repayment schedules.
Shop-top and mixed-use property considerations
Mixed-use premises and shop-top buildings represent a unique valuation scenario for bank credit analysts.
Lenders decide whether to assess a shop-top building under residential or commercial lending guidelines based on floor area distribution, title setup and primary usage.
If the residential dwelling forms the predominant floor space and value, selected lenders may apply residential lending terms and longer loan horizons.
If the commercial trading area dominates the property, lenders classify the asset entirely under commercial guidelines. This usually requires a larger deposit, higher serviceability buffers and periodic loan review clauses.
Financing offices and professional suites
Purchasing a strata office or professional workspace requires examining both the specific lot and the wider strata scheme.
Lenders analyse strata levies, administration fund balances, capital works funds and upcoming maintenance schedules before approving finance.
For business owners looking to owner-occupy a suite, lenders review whether business earnings comfortably meet ongoing strata levies alongside principal and interest payments.
For commercial property investors, credit teams check whether current office leases align with market rental rates for comparable suites in the immediate area.
What checks are needed before making an offer on commercial property?
Before signing a contract or submitting a formal offer on commercial real estate, complete several critical operational checks.
Confirm local council zoning rules allow your planned business activities or intended tenant operations without requiring complex development applications.
Examine lease agreements in detail to verify lease duration, tenant options, rent review structures and outgoings breakdown.
Factor Goods and Services Tax (GST) into your transaction planning, as commercial real estate sales often attract GST unless sold as a going concern with an active lease.
Review strata financial statements to verify there are no large unpaid levies, active litigation or major structural repairs that could diminish the property valuation.
These factors directly influence lender valuation reports and determine how much equity or deposit you must contribute toward the purchase.
How lenders evaluate commercial borrowing capacity
Commercial loan applications focus heavily on debt coverage, property liquidity and historical business cash flow.
Credit teams calculate debt service coverage ratios by comparing your operating cash flow or net rental returns against proposed loan repayments.
Unlike residential home loans that standardly extend up to 30 years, commercial property loans feature shorter repayment terms and structured principal review dates.
For owner-occupier applications, lenders rely on recent tax returns, profit and loss statements and balance sheets to confirm trading stability.
For investor purchases, lenders analyse lease documentation and verified rental income, applying sensitivity checks to ensure debt can be serviced during potential vacant periods.
Preparing comprehensive financial documentation in advance ensures lenders gain a clear view of your capacity to meet ongoing commercial commitments.
How Mortgage Pass helps
Mortgage Pass is located at 1/219 Merrylands Road, Merrylands NSW 2160. Director and founder Julie Judge holds a Diploma of Finance and Mortgage Broking Management, is a member of the MFAA, and is legally required to act in your best interests when recommending a loan. Her background in building, fresh produce and retail means she reads company financials the way a lender does. Mortgage Pass helps business owners and investors compare commercial property loans and structure applications across Sydney, Merrylands, Granville, Holroyd and Rydalmere. For complex or commercial loans, any fee is agreed in writing before work begins.
Frequently asked questions
What checks should I perform before making an offer on a commercial property?
You should verify local council zoning, review lease duration and outgoings, and inspect strata financial statements if applicable. You also need to plan for Goods and Services Tax (GST), as commercial purchases usually attract GST unless sold as a going concern.
How do banks calculate borrowing power for a commercial loan?
Credit teams compare your net rental returns or business operating cash flow against proposed debt repayments using a debt service coverage ratio. They also review recent tax returns, balance sheets, and apply sensitivity checks to account for potential vacancy periods.
How do commercial property loan terms differ from residential mortgages?
Commercial loans typically offer shorter repayment schedules and periodic review dates rather than standard 30-year terms. Lenders also place greater emphasis on property liquidity, local zoning rules, and ongoing business cash flow.
Purchasing commercial property requires thorough preparation, from reviewing council zoning and GST implications to analysing lease stability. Understanding how lenders evaluate commercial risk helps you present a strong application and structure finance effectively. Speaking with a broker allows you to match your financial situation to suitable lender policies across Western Sydney.