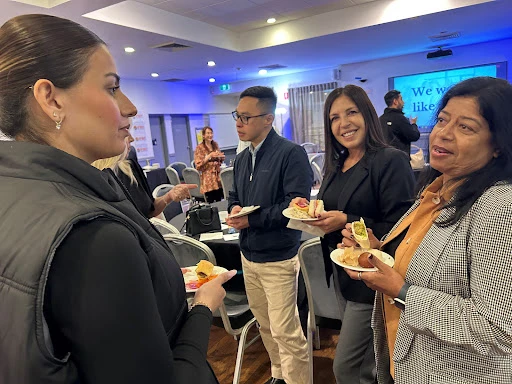
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…A Self-Managed Super Fund can purchase commercial property and lease it back to your business under strict superannuation rules.
On this page
- Can your SMSF buy your business premises?
- How SMSF borrowing works through an LRBA
- Leasing to your own business on commercial terms
- Deposit requirements, upfront costs, and fund liquidity
- What documentation do you need to prepare?
- Who does what: accountants, advisers, and finance brokers
- Risks and operational factors to weigh
- How Mortgage Pass helps
- Frequently asked questions
Many business owners explore buying their commercial premises to gain long-term stability and stop paying rent to third-party landlords. Purchasing commercial property through a Self-Managed Super Fund (SMSF) allows your super fund to hold the physical asset while your operating business becomes the tenant. This arrangement provides a clear pathway to build superannuation wealth while using business rent payments to fund a superannuation asset. However, buying property inside super involves strict regulations set by the Australian Taxation Office (ATO), specialized loan structures, and detailed legal documentation. Understanding how SMSF property transactions work, what lenders require, and how the purchase is structured helps business owners make informed decisions before starting the process.
Can your SMSF buy your business premises?
An SMSF is legally permitted to purchase commercial property and lease it to a business owned by fund members, provided the asset qualifies as business real property.
Business real property generally refers to land and buildings used wholly and exclusively for business purposes, such as offices, warehouses, factories, retail shops, or medical suites. Residential property cannot be leased to fund members or related parties under super regulations.
When an SMSF owns the commercial premises, lease payments made by the operating business flow directly into the super fund as investment income. This allows business owners to build equity inside their superannuation while retaining operational stability for their business.
How SMSF borrowing works through an LRBA
Super funds borrowing money to purchase property must use a Limited Recourse Borrowing Arrangement (LRBA).
Under an LRBA, a separate legal entity known as a bare trust or holding trust holds legal title to the property on behalf of the SMSF until the loan is fully repaid. The SMSF retains beneficial ownership and receives the rental income generated by the property.
The limited recourse structure protects the broader super fund. If the fund defaults on loan repayments, the lender can only repossess the specific property held in that bare trust structure, leaving all other fund assets protected.
Lenders evaluate SMSF loan applications differently from standard home loans. When assessing borrowing capacity, lenders analyze proposed commercial rental income, ongoing member contributions, and existing super fund investment returns to ensure the fund can comfortably service the debt.
Leasing to your own business on commercial terms
The rental agreement between your SMSF and your operating business must operate strictly on an arm's-length basis.
Arm's-length terms mean the lease must reflect normal commercial market conditions. Rent must be paid at current market rates, on time, and according to a formal, legally binding commercial lease agreement.
An independent valuation from a qualified valuer is required to establish fair market rental rates and document compliance for superannuation auditors. Charging above or below market rates to move cash between entities violates super laws and can trigger significant tax penalties from the ATO.
Deposit requirements, upfront costs, and fund liquidity
An SMSF must maintain sufficient liquid capital to cover upfront purchase costs and ongoing operational expenses without relying on external borrowing for non-property costs.
Upfront capital requirements for an SMSF commercial property purchase typically include:
• A substantial cash deposit required by commercial lenders to meet maximum loan-to-value ratio limits.
• Stamp duty on the property transfer assessed by state revenue authorities.
• Legal and conveyancing fees for contract reviews and title transfers.
• Establishment costs for setting up the holding trust and corporate trustee legal structures.
• Valuation fees charged by qualified commercial property valuers.
Ongoing liquidity needs for the fund include:
• Cash reserves to manage council rates, water charges, and building insurance premiums.
• Land tax liabilities applicable to commercial property holdings.
• Annual SMSF accounting, auditing, and regulatory reporting expenses.
• A safety buffer to meet regular loan principal and interest repayments if business rental income changes.
What documentation do you need to prepare?
Applying for an SMSF commercial property loan requires thorough financial documentation from both the super fund and the tenant business.
Lenders require key SMSF documents to verify compliance and financial health:
• The registered SMSF trust deed and current investment strategy document.
• Two to three years of audited SMSF financial statements and annual tax returns.
• Recent bank statements showing available liquid cash reserves.
Lenders also review the operating business financial records to verify that rent is affordable:
• Two years of company financial statements and tax returns for the tenant business.
• Recent Business Activity Statements (BAS) confirming current business cash flow.
• An executed or draft commercial lease agreement specifying rental terms and market rates.
Who does what: accountants, advisers, and finance brokers
Purchasing property inside super requires coordinated input from qualified professionals across tax, legal, and finance disciplines.
Accountants and accredited SMSF advisers verify that the investment aligns with the fund's investment strategy, establish legal bare trust structures, and oversee ongoing ATO compliance.
Finance brokers evaluate borrowing capacity across multiple commercial lenders, compare specialized SMSF loan products, structure credit submissions, and manage the loan process through to settlement.
Solicitors and conveyancers handle property conveyancing, verify commercial lease agreements, and ensure holding trust deeds satisfy lender legal requirements.
Risks and operational factors to weigh
While buying business premises through super offers clear strategic benefits, business owners must evaluate several key risks before proceeding:
• Asset concentration risk arises when a single commercial property represents a substantial proportion of total super fund assets.
• Liquidity constraints occur because property is an illiquid asset that cannot be partially sold to cover unexpected expenses or cash demands.
• Strict regulatory requirements mean failing to maintain market-rate leases or formal lease records can lead to severe ATO compliance penalties.
• Interest rate fluctuations can increase debt servicing costs, requiring higher fund cash reserves to manage economic shifts.
How Mortgage Pass helps
Mortgage Pass helps structure finance through SMSF Property Loans and Commercial Property Loans. Founder Julie Judge holds a Diploma of Finance and Mortgage Broking Management, is an MFAA member, and operates under Australian Credit Licence 387025. She works alongside your accountant and SMSF advisers to compare suitable lenders, prepare your application, and manage settlement.
Frequently asked questions
What types of property qualify as business real property for an SMSF?
Business real property includes land and buildings used wholly and exclusively for business purposes, such as offices, warehouses, factories, retail shops, and medical suites. Residential property cannot be leased to fund members or related parties under super regulations.
How are other super fund assets protected if the property loan defaults?
Under a Limited Recourse Borrowing Arrangement, the lender's security is restricted strictly to the property held in the bare trust. If the fund defaults, the lender can only repossess that specific asset, keeping all other fund assets protected.
How must rent be determined when an SMSF leases property to your business?
Rent must reflect current commercial market rates and be supported by an independent valuation from a qualified valuer. The arrangement must be documented in a formal, legally binding commercial lease agreement.
What tenant business records do lenders review for an SMSF loan application?
Lenders review two years of company financial statements and tax returns, recent Business Activity Statements, and a draft or executed commercial lease agreement. This documentation confirms that the business can comfortably afford the rent.
Purchasing commercial premises through an SMSF offers business owners a structured path toward property ownership and long-term retirement planning. Given the detailed legal and financial rules governing SMSF borrowing, working with qualified accountants, financial advisers, and finance brokers ensures your property strategy remains fully compliant.