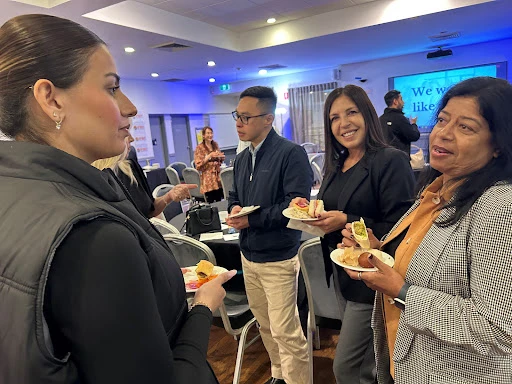
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…A practical guide to how lenders evaluate company profit, trust distributions, add-backs, and trading history when company directors apply for a home loan.
On this page
- Why personal tax returns can understate true borrowing capacity
- How lenders assess discretionary trusts versus unit trusts
- Comparing retained company profit and dividend distributions
- Understanding legitimate add-backs in business calculations
- Impact of trading history length on lender selection
- Full doc versus low doc loan options
- How to prepare your business and trust financials before applying
- How Mortgage Pass helps
- Frequently asked questions
Standard bank automated credit systems look for regular PAYG payslips and group certificates. When an applicant is a company director or receives income through a trust, these standard algorithms often miscalculate borrowing power by focusing solely on taxable personal income. Understanding how credit assessors evaluate company financials, trust structures, and business earnings helps ensure your true capacity to pay is recognised.
Why personal tax returns can understate true borrowing capacity
Tax minimisation strategies, salary drawing choices, and retained earnings mean a director's personal tax return often shows lower income than the business generates. Accountants naturally design financial statements to minimise tax liabilities by keeping profits within a company or distributing them efficiently across family members.
While this approach protects operating cash flow, bank credit assessors focused only on individual notices of assessment can misinterpret low personal drawings as a lack of borrowing capacity. Evaluating the underlying business financial reports provides a complete view of available cash flow.
How lenders assess discretionary trusts versus unit trusts
Lenders view trust income differently depending on whether the structure is a discretionary trust or a unit trust. Discretionary trusts allow trustees to vary income distributions each financial year, which causes some lenders to treat these payments as variable or non-recurring.
To accept discretionary trust income, credit assessors usually require a two-year history showing consistent distributions to the same beneficiary. They will examine trust tax returns, financial statements, and individual notices of assessment to confirm the income stream is stable.
Unit trusts distribute income based on fixed unit holdings held by unit holders. Because unit ownership represents a fixed equity percentage, lenders evaluate unit trust distributions more like standard corporate dividends, provided the underlying trust entity maintains profitable trading operations.
Comparing retained company profit and dividend distributions
Dividend distributions paid out to personal bank accounts appear directly on individual tax returns, making them easy for standard credit models to recognise. Retained profit left inside the trading company account requires a deeper policy assessment.
Some lenders will add your share of net company profit before tax to your personal income, provided you own a controlling share in the business. Other lenders ignore retained earnings entirely, assessing only the salary or dividends actually drawn down into your personal name.
Where a business has multiple non-related directors, lenders may require written consent or evidence of ownership percentages before including retained net profit in serviceability calculations.
Understanding legitimate add-backs in business calculations
Add-backs are legitimate business expenses recorded in company financial statements that lenders can add back to net profit to establish true operational cash flow. Adding these non-cash or non-recurring expenses back increases your assessed serviceability without changing your tax strategy.
Common add-backs include non-cash depreciation on business equipment and vehicles, voluntary director superannuation contributions, and net interest expenses paid on existing business loans that will not continue post-settlement.
Identifying these line items requires reviewing balance sheets and profit and loss statements line by line before lodging a home loan application.
Impact of trading history length on lender selection
Most mainstream banks prefer a full two-year trading history under the current business structure before assessing a self-employed or company director application. Lenders typically average the net profit across both financial years or take the lower year if profit has decreased.
Select lenders accept a one-year trading history if the applicant worked in the same industry as a PAYG employee or sole trader immediately before establishing the proprietary limited company. These policies accommodate recent structure changes without imposing unnecessary delays.
Full doc versus low doc loan options
Full doc applications require comprehensive documentation, including two years of company tax returns, financial statements, notices of assessment, and trust returns. You can review standard pathways under home loans or explore specialised structures under self-employed loans.
Low doc or alt-doc options assist directors who do not have fully up-to-date tax returns prepared by their accountant. These products verify trading turnover using business bank statements, official activity statements, or accountant declarations instead of lodged tax returns.
How to prepare your business and trust financials before applying
Preparing complete financial records before approaching a lender prevents unnecessary processing delays or declined credit decisions. Gather signed tax returns for all trading entities, trust deeds, corporate tax portal running balance accounts, and notices of assessment.
Meeting with your accountant to review balance sheet liabilities, such as director loan accounts or outstanding ATO tax debts, allows you to resolve potential credit questions before your application undergoes formal assessment.
How Mortgage Pass helps
How Mortgage Pass helps Julie Judge spent years working with businesses in building, fresh produce and retail, so she reads a set of company financials the way a lender will. That is why self-employed, construction and business borrowers make up much of her work. Based on Merrylands Road in Merrylands, Mortgage Pass is a mortgage broker and finance broker helping company directors, trust beneficiaries, professionals and self-employed borrowers structure their lending. Legally required to act in your best interests, Julie compares lender policies across dozens of banks to match your income structure to a suitable home loan.
Frequently asked questions
What are common add-backs that can increase borrowing power for business owners?
Common add-backs include non-cash depreciation on business equipment, voluntary director superannuation contributions, and net interest expenses on loans that will not continue post-settlement. Lenders add these non-cash or non-recurring expenses back to net profit to determine your actual operational cash flow.
How do low doc or alt-doc loans work if tax returns are not ready?
Low doc or alt-doc options verify your trading turnover using business bank statements, official activity statements, or accountant declarations. This allows company directors to demonstrate serviceability without providing fully lodged personal and business tax returns.
How do unit trust distributions differ from discretionary trust income?
Unit trust distributions are based on fixed equity percentages, so lenders evaluate them similarly to corporate dividends if the trust is trading profitably. Discretionary trust distributions can vary each year, which leads credit assessors to require a two-year history of consistent distributions to the beneficiary.
Why might personal tax returns understate a director's true borrowing capacity?
Personal tax returns may reflect lower income due to salary drawing choices, tax minimisation strategies, or net profit retained within the business. Automated bank systems assessing only personal notices of assessment can misinterpret these lower personal drawings as a lack of income.
Navigating home loan applications as a company director or trust beneficiary requires an approach tailored to how credit assessors analyze complex income. By understanding how lenders view retained profit, trust allocations, add-backs, and trading history, you can present your financial position accurately. The right pathway depends on your business structure, documentation status, and long-term financial goals.