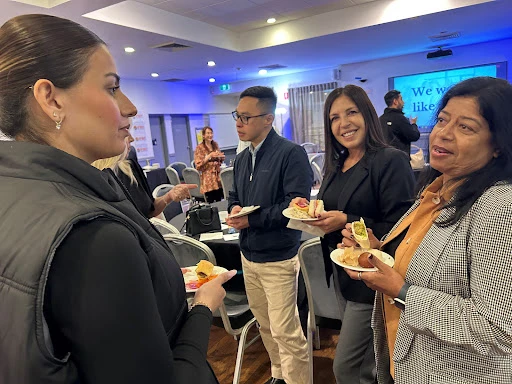
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…Learn how Australian mortgage brokers are paid, who pays their commission, when direct fees apply, and how legal duties protect borrowers.
On this page
Borrowers often want to know whether using a mortgage broker costs them extra money or influences which home loan is recommended. In Australia, the fee structure for mortgage broking is regulated to provide transparency and consumer protection. Understanding how finance brokers receive commissions, when direct service fees apply, and how the law governs broker recommendations helps you weigh up your options clearly. Whether you are buying a first home, refinancing, or securing business finance, knowing how your broker is paid ensures you can ask the right questions before applying.
How do mortgage brokers get paid in Australia?
Most residential mortgage brokers in Australia operate without charging the borrower a direct service fee. Instead, brokers receive payment directly from the lending institution that provides your loan once the transaction completes.
This arrangement allows home buyers, self-employed borrowers, and property investors to access professional credit guidance, market comparisons, and application management without adding upfront out-of-pocket costs.
To explore how brokers evaluate loan options compared to visiting a bank branch directly, you can read our guide on broker or bank?.
Who pays the broker's commission?
The financial institution providing your loan pays the broker a commission after your loan settles. This payment rewards the broker for completing administrative and analytical tasks that bank staff would otherwise perform.
A broker gathers financial documentation, checks your details against lender policies, and prepares a completed application. Because lenders assess income, deposits, and credit files differently, a broker identifies suitable lenders before submitting an application.
Matching your situation to the right lender before applying helps avoid unnecessary declined applications on your credit file.
When might a broker charge a direct fee?
While standard residential home loans rarely involve direct costs to the borrower, specific situations may lead a broker to charge a service fee. This occurs most often in complex commercial transactions, business lending, or specialised finance structures requiring extensive custom work.
If a broker does charge a direct fee, Australian regulations require them to disclose this payment structure clearly before doing work on your behalf. Details regarding fee disclosures and arrangements are available on our fees page.
Always ensure you receive a clear explanation of any potential fee upfront so there are no surprises during the application process.
How does the Best Interests Duty protect borrowers?
Australian law requires mortgage brokers to abide by a statutory Best Interests Duty when recommending consumer credit products. This legal obligation requires brokers to prioritise your financial interests above their own or those of any lender.
Under this duty, a broker cannot suggest a loan simply because it pays a higher commission if another available loan better suits your needs. The broker compares multiple lenders' policies, features, and trade-offs rather than focusing only on advertised interest rates.
A broker evaluates whether a loan suits your specific circumstances, such as having self-employed income, construction plans, a small deposit, or a past credit issue.
How do you check a broker's licence and ask about fees?
Before working with a broker, you can verify their qualifications and regulatory standing by checking their credit representative or licence number on the official ASIC register.
When meeting a broker for the first time, asking direct questions about their process and payment structure helps you make an informed choice. Consider asking the following key questions:
* How many lenders do you compare across your panel?
* How are you paid for managing this transaction?
* Have you handled applications for clients with financial situations like mine?
* What specific debts, accounts, or changes to my job do I need to declare?
Being fully upfront about all financial details, including buy-now-pay-later accounts, credit card limits, past defaults, and job changes, ensures your application moves forward without unexpected delays.
How Mortgage Pass helps
Julie Judge, founder and finance broker at Mortgage Pass on Merrylands Road, holds a Diploma of Finance and Mortgage Broking Management and is a member of the MFAA. Having spent years working with businesses in building, fresh produce, and retail, Julie reads company financials the way a lender does, making Mortgage Pass well suited for self-employed, construction, and business borrowers. As legally required, Mortgage Pass acts in your best interests, providing plain explanations of all options and fee arrangements across home, commercial, self-employed, and business finance.
Frequently asked questions
Is a mortgage broker the same as a finance broker?
A mortgage broker usually focuses on home loans, while a finance broker covers wider lending such as car, business and equipment finance. Mortgage Pass provides both services.
How does the Best Interests Duty protect me?
The Best Interests Duty legally requires brokers to prioritise your financial interests over their own commission. A broker cannot suggest a loan simply because it pays them more if another available loan suits you better.
When might a broker charge a direct fee?
Direct service fees are uncommon for standard home loans and usually apply to complex commercial or business finance arrangements. Any direct fee must be fully explained to you before the broker begins work.
Is using a mortgage broker worth it for complex financial situations?
Using a broker is worth it when you have self-employed income, construction plans, a small deposit or a past credit issue. A broker compares policy differences across multiple lenders and handles the application paperwork.
Understanding how mortgage broker fees and commissions work gives you confidence when navigating property and business finance. Lender-paid commissions make professional credit advice accessible for home buyers, while statutory duties ensure your financial interests remain the top priority. Asking clear questions about payment structures and checking credentials allows you to choose the right broker for your financial goals.