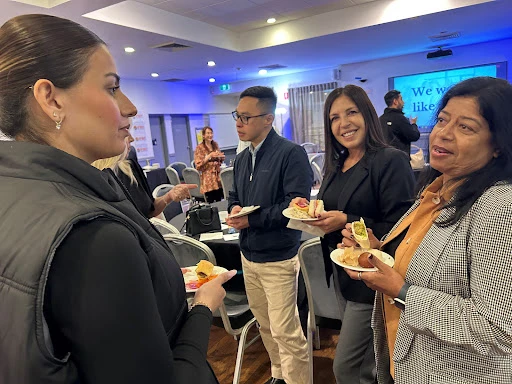
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…Understanding how banks evaluate variable pay, contractor rates and probation periods helps you present your income clearly and evaluate your home loan options.
On this page
Online borrowing calculators default to base salaries, causing borrowers with variable pay to significantly underestimate their true borrowing capacity. When your earnings include bonuses, sales commissions, overtime or contract daily rates, standard online assessment forms often fail to capture your full income. Knowing how different credit assessors evaluate non-standard pay structures allows you to position your home loan application effectively and avoid unnecessary declined applications.
How lenders treat bonuses and variable pay
Banks treat bonus payments differently from standard base salary because bonuses are considered variable pay. Some credit assessment policies shade or reduce the bonus amount by a set percentage, while others require a consecutive two-year history of bonus payments before counting them toward your borrowing power.
Other institutions may accept a shorter history if you remain in a similar line of work or demonstrate a strong track record with the same employer. To establish this history, credit assessors usually request your recent PAYG payment summaries, tax returns and official Australian Taxation Office notice of assessments.
Calculating your serviceability accurately relies on choosing a lender whose policy matches your specific payment structure. Borrowers can explore how these assessments affect their overall position by reviewing their estimated borrowing power across different policy frameworks at /borrowing-power.
Commission and overtime income assessments
Regular commission and overtime payments provide significant income for many sales specialists and consultants, yet credit teams treat them as fluctuating earnings. Lenders typically average these payments over a six to twenty-four month period to establish a reliable baseline.
If your commission income increases year on year, some credit assessors average the two years, while others adopt a conservative approach by taking the lower year's figure. This structural difference means two lenders reviewing identical pay slips can calculate vastly different maximum loan amounts.
Providing thorough documentation, such as year-to-date pay slips, group certificates and end-of-financial-year tax statements, ensures assessors calculate your true earning baseline. Medical specialists, corporate consultants and sales executives seeking high-capacity loans often benefit from finance for professionals policies tailored to variable earnings structures at /finance-for-professionals.
Contractors, day rates and self-employed requirements
Independent contractors, fixed-term workers and daily rate professionals are assessed based on contract stability, industry continuity and remaining contract length. While standard bank guidelines often demand two full years of self-employed tax returns, specialized policies accommodate PAYG contractors and daily rate workers with shorter track records.
To verify serviceability, credit assessors evaluate formal letters of offer, current signed service contracts, recent pay slips and tax assessment notices. They check whether your contract has a history of renewals and verify that you have maintained continuous employment within the same industry without extended gaps.
Daily rate contractors can have their income annualised by certain lenders, provided their contract structure satisfies specific credit criteria. Contractors who operate through a company structure or trust may instead require self-employed loans policies designed to unpack company financial statements and tax filings at /self-employed-loans.
New jobs and probation periods
Changing roles or remaining within a probationary period does not automatically rule out home loan approval, though it reduces the pool of willing lenders. Conservative credit policies require probation periods to be fully completed before recognizing new income.
However, several lenders accept applications from borrowers currently on probation, provided the new role is within the same line of work or represents a direct career promotion. Credit assessors examine your employment contract, letter of offer and final pay slip from your previous employer to confirm career continuity.
Supplying clear evidence of uninterrupted employment history helps assessors verify stability, protecting your credit record from unnecessary declined applications caused by applying to non-complying lenders.
Salary packaging, allowances and fringe benefits
Salary packaging arrangements, such as novated vehicle leases, packaged superannuation contributions or meal cards, alter your taxable gross income on paper. Credit assessors examine itemised pay slips and employment agreements to decide whether packaged items act as living expenses or re-add to your gross income.
Workplace allowances, including car, travel or uniform allowances, are also handled differently across the market. Some lenders include regular allowances as full gross income, while others treat them as expense reimbursements and exclude them from serviceability calculations.
Providing itemised pay slips alongside complete employment contracts ensures assessors classify every packaged benefit accurately when determining your final borrowing capacity.
How Mortgage Pass helps
Julie Judge at Mortgage Pass brings years of experience working with business financials to help professionals and contract workers navigate lender policies. As a mortgage broker based in Merrylands, Mortgage Pass is legally required to act in your best interests, matching your unique bonus, commission or contract income with suitable home loan options across multiple lenders.
Frequently asked questions
What documents are required to prove bonus income?
Credit assessors usually request your recent PAYG payment summaries, tax returns and official Australian Taxation Office notice of assessments. These documents establish your history of bonus payments.
How do lenders assess workplace allowances like car or travel pay?
Some lenders include regular allowances as full gross income when calculating borrowing capacity. Others treat allowances as expense reimbursements and exclude them from serviceability calculations.
How is rising commission income evaluated by credit teams?
When commission income increases year on year, some credit assessors average the earnings over two years, while others take the lower year's figure. Providing year-to-date pay slips and tax statements helps prove your baseline income.
What do lenders check when assessing daily rate contractors?
Lenders evaluate signed service contracts, letters of offer, pay slips and tax notices to confirm contract stability. They verify whether your contract has a history of renewals and continuous industry employment without extended gaps.
Getting approved for a home loan with bonus, commission, contractor or allowance income relies on matching your income structure with a lender whose credit guidelines cater to your situation. Presenting complete documentation and reviewing policy variations across lenders ensures your actual borrowing capacity is recognized.