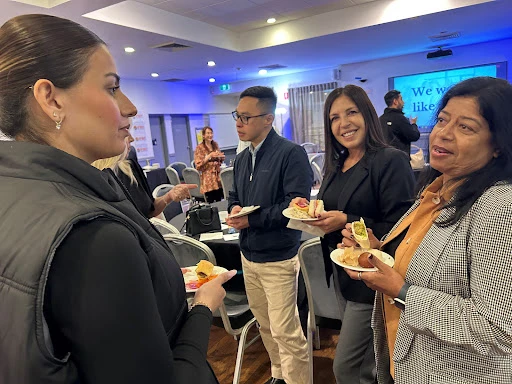
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…Understanding how a mortgage broker compares to going directly to a bank can help you decide the best path for your loan application.
On this page
- Choice of lenders across the market
- How lender policies affect borrowing power and approvals
- Best interests duty and legal obligations
- Application management and pre-approvals
- How broker commissions and fees work
- When going straight to your bank makes sense
- How to decide which path suits you
- How Mortgage Pass helps
- Frequently asked questions
Applying directly to a bank limits your choices to that single institution, while using a mortgage broker gives you access to multiple lenders across the market. Banks assess applications strictly against their own internal credit criteria and product lists. A broker evaluates your income, deposit, and goals first, then matches you with lenders whose credit policies suit your situation. Understanding these practical differences helps you decide which approach fits your borrowing needs.
Choice of lenders across the market
Approaching a bank directly limits your options to what that specific institution offers on the day.
Working with a mortgage broker allows you to compare multiple lenders side by side.
Having access to a broader selection makes it easier to evaluate loan features, ongoing fees, and repayment structures without submitting separate applications to multiple institutions.
How lender policies affect borrowing power and approvals
Loan approval depends heavily on how a bank calculates your borrowing capacity and assesses your income.
Lenders assess income, deposit, and credit history differently across various borrower scenarios:
* How overtime, bonuses, or commission payments are calculated as acceptable income.
* How self-employed earnings, company profits, and tax structures are evaluated.
* The size of the deposit required to avoid paying lender risk fees.
A broker understands how different credit policies apply to your situation, helping avoid unnecessary declined applications on your credit file.
Best interests duty and legal obligations
Bank staff are employees who act on behalf of their institution and its lending targets.
Licensed mortgage brokers are bound by a legal requirement to act in your best interests when recommending a home loan.
This legal duty ensures a broker must prioritise your financial interests over lender preferences when recommending a home loan product.
Application management and pre-approvals
Managing a loan application involves gathering paperwork, submitting financial records, and tracking progress through to settlement.
When you apply directly to a lender, you manage communications directly with that bank's internal team.
A broker finds suitable lenders, prepares the application, and manages the entire process through to settlement on your behalf.
Brokers also help explain pre-approval steps so you understand your position before making an offer on a property.
How broker commissions and fees work
Understanding how a broker is paid helps clarify the financial side of using an intermediary.
For most home loans, using a broker costs you nothing because the lender pays the broker a commission after the loan settles.
If a fee ever applies, such as on some complex or commercial loans, it is agreed with you in writing before any work begins.
When going straight to your bank makes sense
Applying directly to your current bank can be a practical option under specific circumstances.
If you have a clear credit history, standard salary income, and a strong deposit, your bank may offer a sharp rate with minimal setup effort.
Going direct can suit borrowers with simple financial needs who prefer managing all accounts with one institution and already hold an offer they are completely satisfied with.
How to decide which path suits you
Evaluating your personal circumstances will help determine which path fits best.
Consider reviewing broker or bank options if you want to compare multiple lenders or have complex income structures such as self-employed loans.
Consider going straight to a bank if your financial situation is simple and you prefer dealing exclusively with your existing lender.
How Mortgage Pass helps
Mortgage Pass is a mortgage broker based at 1/219 Merrylands Road, Merrylands. Founder Julie Judge holds a Diploma of Finance and Mortgage Broking Management and is legally required to act in your best interests when recommending a loan. Mortgage Pass compares options across 35+ lenders for home, business, and car loans. For most home loans, there is no cost to you because the lender pays a commission when your loan settles.
Frequently asked questions
How much does it cost to see a mortgage broker?
For most home loans, seeing a broker costs nothing because the lender pays a commission when your loan settles. If a fee ever applies for complex or commercial loans, it is agreed with you in writing before any work starts.
Is it easier to get a loan through a mortgage broker?
It is not necessarily easier, but a broker knows how different lenders evaluate income and deposit requirements. Matching you with suitable lenders before you apply helps avoid unnecessary declined applications on your credit file.
What is the difference between a mortgage broker and a finance broker?
A mortgage broker mainly assists with home loans, whereas a finance broker handles wider lending such as car, business and equipment finance. Mortgage Pass acts as both, so home and business lending can be planned together.
When does it make sense to go straight to a lender?
Going direct can suit borrowers who have a straightforward application, standard salary income, a strong deposit and a preferred bank whose offer they are already happy with.
Deciding between a broker and a bank comes down to the level of market choice, policy matching, and support you require. A direct approach to your bank can work well for simple circumstances when you already hold a competitive offer. Working with a mortgage broker gives you access to multiple lenders and credit policies, backed by a legal duty to act in your best interests.