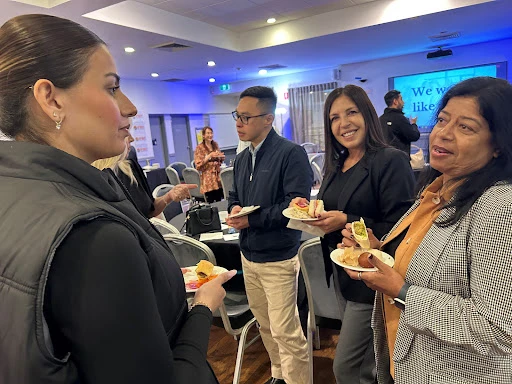
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…A practical guide to the tax returns, balance sheets and bank statements self-employed borrowers need when applying for finance.
On this page
Applying for a home or business loan when running your own business involves a different assessment process than a standard wage-earner application. Credit assessors look past basic earnings to verify that your business income is stable, recurring, and sufficient to service loan repayments over time. Because self-employed operating structures vary across sole traders, company directors, and trusts, preparing the exact paperwork a lender needs reduces processing delays. Understanding how credit assessors evaluate self-employed documentation helps you present a clear financial position before submitting your application.
The core checklist for self-employed borrowers
Every self-employed loan application begins with proof of identity and general personal financial records. Lenders review your personal situation before evaluating the operating figures of your business.
Standard personal documentation required across most lending assessment pathways includes:
Primary photo identification such as a driver licence or passport.
Personal tax returns for recent financial years as required by individual lender policy.
Notices of Assessment issued by the Australian Taxation Office corresponding to lodged returns.
Personal transaction and savings bank account statements showing general living expenses and existing liabilities.
Credit assessors examine these personal records to confirm reported taxable income and verify existing financial commitments. Providing clear and complete paperwork from the start helps prevent repeated queries during loan underwriting.
Documents required by entity structure
Your business operating structure determines which additional financial statements a credit assessor must analyze. Lenders examine entity financial records to determine the underlying strength and trading stability of the business.
Specific paperwork requirements vary depending on how your business is legally set up:
Sole traders report trading income on individual returns, requiring personal tax returns with business schedules and profit and loss statements.
Company directors must supply financial accounts for the operating company alongside personal tax returns to show director wages and retained earnings.
Trusts require formal trust deeds together with financial statements and tax returns showing distribution details to beneficiaries.
Lenders review balance sheets and profit and loss accounts to ensure the business is trading solvently. Understanding entity-specific requirements prevents delays caused by missing corporate schedules or unverified trust distributions.
Low doc and alt doc documentation options
Borrowers who do not have fully lodged tax returns or completed financial statements may consider alternative documentation options. These pathways allow lenders to assess servicing capability using alternative proofs of ongoing business turnover.
Alternative documents accepted under specific credit provider policies include:
Business Activity Statements lodged with the Australian Taxation Office showing recent trading activity.
Primary business trading bank account statements reflecting ongoing cash flow.
A formal declaration signed by a qualified accountant confirming business turnover and solvency.
Policy guidelines for an alt-doc pathway differ across credit providers and may involve distinct deposit requirements or loan terms. Working with a broker helps match alternative trading proofs against lender guidelines before applying.
Why lenders examine add-backs and business expenses
Credit assessors evaluate net profit alongside legitimate business expenses that can be added back to taxable income. Add-backs recognise non-cash expenses or one-off costs that do not reflect ongoing operational expenses.
Items frequently considered for potential add-backs during credit assessment include:
Depreciation expenses recorded on business balance sheets.
One-off capital purchases or extraordinary business expenses that will not recur.
Additional superannuation contributions made above mandatory statutory thresholds.
Interest expenses paid on existing debts that will be refinanced or cleared at settlement.
Presenting accurate details of business expenses ensures credit assessors calculate true cash flow available for servicing. Proper documentation of these figures helps reflect your actual capacity to manage loan repayments.
Common hold-ups and how to avoid them
Unlodged tax returns are a common cause of delay for self-employed loan applications. Most credit providers require your most recent eligible financial year to be fully lodged with the Australian Taxation Office before assessing a standard application.
Outstanding tax debts or formal payment arrangements with the Australian Taxation Office must be disclosed upfront. Having an existing tax liability does not automatically prevent approval, but credit assessors need a clear picture of how the liability is managed.
Mixing personal and business expenses within a single bank account can slow down assessment during credit checks. Maintaining separate bank accounts for business operations and personal living expenses establishes clean records for underwriting.
How Mortgage Pass helps
Julie Judge helps self-employed borrowers, tradies, and business owners from her Merrylands office at 1/219 Merrylands Road, Merrylands NSW. Having worked across building, fresh produce and retail before broking, she reads company financials, profit and loss statements, and tax returns from a lender perspective. Mortgage Pass matches applicants with suitable options across 35+ lenders, with no broker fee for most standard home loans. You can reach Mortgage Pass on 0455 510 512 or info@mortgagepass.com.au.
Frequently asked questions
What are add-backs on a self-employed loan application?
Add-backs are legitimate business expenses, such as depreciation or non-recurring costs, that credit assessors add back to net profit to calculate your true cash flow.
Why is it important to keep personal and business bank accounts separate?
Mixing personal and business expenses in a single account can slow down underwriting. Separate accounts provide clean records of your living expenses and business trading.
What paperwork do company directors need to provide?
Company directors must supply personal tax returns alongside financial accounts for the operating company. This shows credit assessors both your director wages and retained earnings.
What documents are required for a loan if my business operates through a trust?
Trust applications require formal trust deeds along with financial statements and tax returns. These documents verify income distribution details to beneficiaries.
Gathering the required financial paperwork before submitting a loan application saves time and protects your credit history. Whether you operate as a sole trader, company director, or through a trust, presenting clear records helps lenders evaluate your true earnings. Comparing lender criteria against your documentation helps ensure your application highlights your business strength without unnecessary delays.