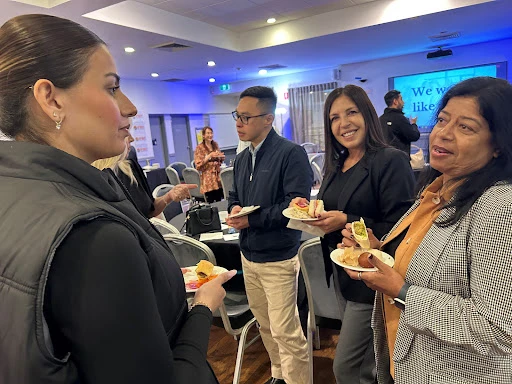
Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with fellow brokers, sharing knowledge, ideas, a little laughter and some delicious treats! I genuinely believe we're better when we learn from each other, support one another and grow together. Business and the market will always have their ups and downs, but we don't have to navigate every season alone. Here's to good connections, supporting each other and remembering that brighter opportunities are always ahead. 🥂
Learn more: Let's ride the wave. 🌊❤️ A lovely way to wrap up the year with…Discover your options when a fixed rate loan expires and learn how to review your home loan before it rolls over.
On this page
When a fixed-rate home loan term comes to an end, borrowers face an immediate change in their monthly household budget. Most mortgage contracts specify that once the fixed period finishes, the loan automatically reverts to the lender standard variable rate. Because default revert rates are often higher than discounted variable rates or current fixed options, staying on the automatic rate without reviewing your setup can lead to higher interest costs. Understanding your choices early gives you control over your mortgage structure and helps you avoid unnecessary repayments.
What happens when your fixed rate ends
When your fixed term finishes, the fixed interest rate and set repayment amount expire. Your loan balance automatically rolls over onto your lender standard variable rate unless you take action before the end date.
Default variable rates are frequently higher than competitive variable rates available in the market. As a result, your minimum monthly repayments can rise as soon as the automatic rollover takes place.
Understanding how this rollover functions allows you to plan ahead and avoid paying excess interest. Reviewing your loan arrangements early ensures you remain in control of your household budget.
Your options before your fixed rate expires
Borrowers have several pathways to consider before a fixed rate term expires. Evaluating each option helps you select a structure that suits your ongoing financial goals and monthly cash flow needs.
- Request a lower retention rate from your current lender to lower your variable interest charges.
- Refix your loan balance for a new fixed term to secure repayment certainty for another set period.
- Switch your balance to a variable rate loan to access flexible features like redraw and offset accounts.
- Split your loan balance between fixed and variable options to combine repayment certainty with feature flexibility.
- Refinance your home loan to a new credit provider offering terms that better align with your financial situation.
When to start reviewing your loan
Starting your loan review early gives you enough time to explore market options and evaluate lender policies. Beginning the process well before your fixed term finishes prevents rushed decisions and costly delays.
Lenders require adequate time to assess applications, arrange property valuations, and process discharge paperwork. Starting early allows you to transition smoothly without spending weeks paying an expensive default variable rate.
Early preparation also gives you time to gather necessary financial documents without pressure. Collecting pay slips, tax returns, and bank statements ahead of time keeps the review organized.
How lender policy differences affect your options
Credit providers assess income, deposit size, and credit history using different internal criteria. A policy that suits one borrower may lead to an unfavorable assessment or a decline with another bank.
Variable income structures require careful evaluation during a home loan review. Borrowers paid through commission, bonuses, overtime, or contract arrangements are assessed differently across various credit providers.
Self-employed borrowers and business owners encounter specific guidelines when reviewing or refinancing a mortgage. Lenders scrutinize company financials, trust structures, and tax returns differently, which directly impacts borrowing capacity.
Deposit size and existing equity also determine which lenders can offer suitable home loan products. Certain lenders cater better to lower deposit thresholds, while others require specific equity levels to avoid extra costs.
Submitting an application to an unaligned lender can lead to an unnecessary decline on your credit file. Comparing policy guidelines before applying helps match your financial profile with an appropriate credit provider.
Costs to check before making a move
Checking potential fees ensures that changing loan structures or switching credit providers delivers a true financial benefit. Comparing total costs against potential savings helps you determine whether refinancing makes sense.
Break costs generally do not apply when a fixed rate term naturally expires on its agreed end date. However, exiting a fixed rate period early can trigger substantial break fees calculated by the lender.
Switching lenders or establishing a new loan facility may involve standard administrative charges. Common expenses include lender application fees, valuation fees, settlement fees, and government mortgage registration costs.
Discharge fees are typically charged by your existing lender to release the mortgage title upon leaving. Checking these charges in advance ensures there are no unexpected costs during the rollover process.
How refinancing works
Refinancing involves replacing your current home loan with a new loan from your existing lender or a different credit provider. The process begins by comparing loan policies, interest structures, and features across multiple lenders.
Preparing your financial documentation is the next step in the refinancing application. Lenders require recent pay slips, bank statements, personal identification, and tax documents to verify your income and living expenses.
The credit provider evaluates your financial position, assesses credit risk, and orders a property valuation. Once approved, the new lender coordinates with your current institution to settle the old loan and finalize the transfer.
A clear refinancing plan ensures a smooth transition between loan agreements. Reviewing your mortgage arrangements periodically keeps your loan aligned with changes in your income and household requirements.
How Mortgage Pass helps
Mortgage Pass is a mortgage broker based at 1/219 Merrylands Road, Merrylands NSW. Director Julie Judge holds a Diploma of Finance and Mortgage Broking Management and is legally required to act in your best interests when recommending a loan. For most home loans, seeing Mortgage Pass costs nothing because the lender pays a commission when the loan settles. Whether you want to explore refinance loans, check home loans, or compare options on self-employed loans, Mortgage Pass compares policies across 35+ lenders to help you navigate your choices.
Frequently asked questions
When should I start reviewing my loan before my fixed rate expires?
Starting early gives lenders enough time to assess your application, arrange property valuations, and process discharge paperwork. This helps you transition smoothly without spending weeks paying an expensive default variable rate.
Do break costs apply when a fixed rate term naturally finishes?
Break costs generally do not apply when your fixed rate term naturally expires on its agreed end date. They usually only apply if you exit or break a fixed period before it ends.
What features can I access by switching to a variable rate?
Switching your loan balance to a variable rate allows you to access flexible features such as offset accounts and redraw facilities.
What documents do I need to gather for a loan review or refinance?
Lenders typically require recent pay slips, bank statements, personal identification, and tax documents to verify your income and living expenses.
When your fixed home loan rate expires, doing nothing can result in higher interest costs on a default variable rate. By planning early, checking discharge fees, and evaluating lender policies, you can choose a loan structure aligned with your household budget. The right choice depends on your individual situation and whether you prefer fixed certainty, variable flexibility, or a combination of both.